

TL;DR
- Accounts receivable financing turns money your customers already owe you, such as unpaid invoices or card sales waiting to settle, into cash today. A funder pays you most of the value now and keeps a fee.
- There are five main types: factoring, invoice financing, asset-based lending, supply chain finance and card settlement financing. They differ in who collects, who carries the loss and how long the money is out.
- The cost is usually a fee per period, so slow-paying customers cost more. Turn any fee into a yearly figure before you compare it with a bank loan.
- Demand is real: in the Fed's latest small business survey, 56% of firms that sought financing did so to meet operating expenses.
- CREDI works on the funding side. Liquidity providers deposit stablecoins into a CREDI vault, vault capital finances card and trade payments waiting to settle, and the rate is fixed on the day of deposit.
Every business that sells first and gets paid later has the same gap. The work is done or the card has been tapped, and the money still hasn't arrived.
Accounts receivable financing fills that gap by paying the business now against money it's already owed.
This guide explains how it works in plain terms, the five main types, what it really costs, what funders look at, and who puts up the money, including where CREDI fits.
What Is Accounts Receivable Financing?
Accounts receivable financing is a way for a business to get cash now against money its customers owe it later.
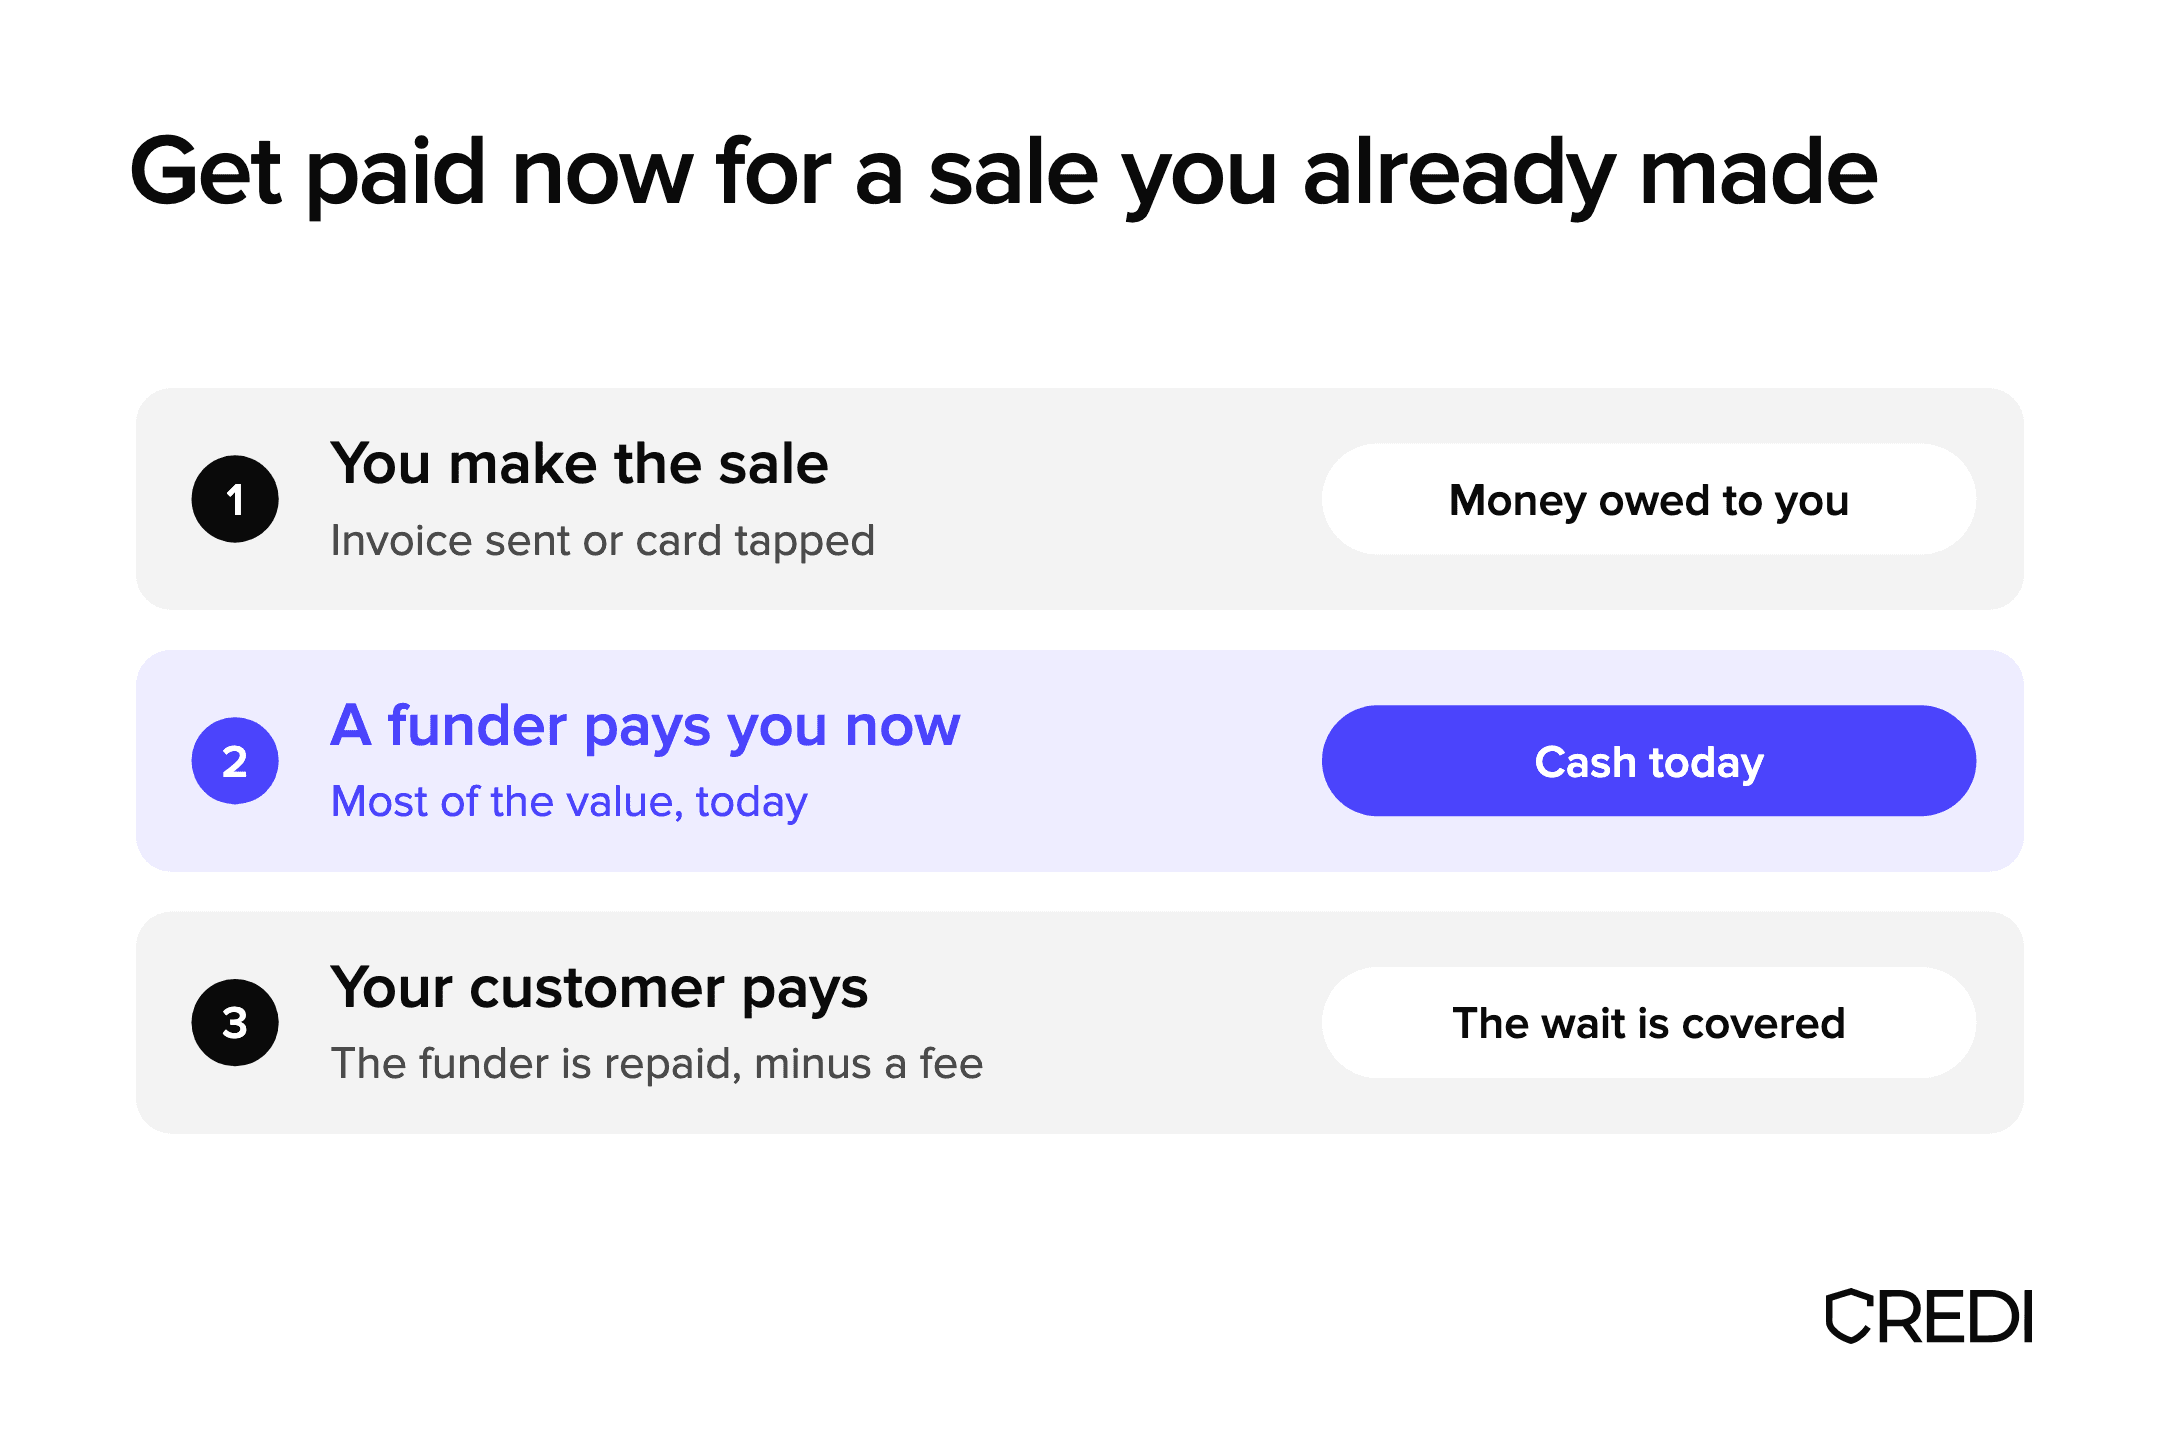
A funder advances a share of the value of unpaid invoices or card sales, gets repaid when the customer pays, and keeps a fee. It's also called receivables financing.
Accounts receivable (AR) is the accounting name for sales you've made and haven't been paid for yet. A supplier that invoices on "net 60" terms, meaning the customer has 60 days to pay, waits up to two months.
A shop that takes a card payment waits for the card network and the acquirer, the bank or processor that handles card payments for the shop, to send the money. That usually takes a few days.
Our guide to how credit card payments work walks through each step.
In both cases the sale has already happened. Receivables financing lets the business use that money before it arrives.
Card sales waiting to settle are the receivables CREDI vaults finance. Vault capital covers the wait between the swipe and settlement, and the vault is repaid when the payment settles.
Why Businesses Use Receivables Financing
Bills arrive before customer payments do, and bank loans are not always available or fast. Payroll, rent and suppliers are due every month.
Customer money arrives on the customer's schedule.
The numbers show the gap. In the Federal Reserve Banks' 2026 Report on Employer Firms, 60% of small firms applied for financing in the prior 12 months.
The most common reason was to meet operating expenses (56%). Only 42% of applicants got the full amount they asked for, and 22% got nothing.
Bank credit has also become more expensive.
In the ECB's Survey on the Access to Finance of Enterprises for the second quarter of 2026, a net 43% of euro area small and medium firms reported higher bank loan interest rates, up from 24% the quarter before.
In the UK, the British Business Bank's Small Business Finance Markets 2025/26 report found that working capital, the money a business needs to run day to day, was the main reason small firms used finance in 2025, cited by 50%.
Receivables financing helps because the funder looks mainly at the receivable and the customer who owes it.
Card merchants feel a short version of this gap: a few days between the sale and the money. Our guide to why merchants wait days to get paid explains why.
CREDI finances that settlement cycle, so the merchant is paid sooner.
The 5 Main Types of Accounts Receivable Financing
The five main types are factoring, invoice financing, asset-based lending, supply chain finance and card settlement financing. All of them advance cash against receivables.
They differ in whether the receivable is sold or used as security, who collects, and who absorbs a customer default.
| Type | How it works | Who collects from the customer | Who usually carries a default | Typical user |
|---|---|---|---|---|
| Factoring | You sell invoices to a factor at a discount | The factor | You (recourse) or the factor (non-recourse) | B2B firms with slow payers and little credit history |
| Invoice financing | You borrow against invoices and keep them | You | You | Firms that want to keep customer relationships in-house |
| Asset-based lending (ABL) | A credit line sized by your eligible receivables, and often inventory | You | You | Mid-sized and larger companies |
| Supply chain finance | A large buyer's bank pays approved supplier invoices early | The funder, from the buyer | Mostly the buyer | Suppliers to large, reliable buyers |
| Card settlement financing | Card sales are paid out before they settle | Repaid from card settlement | Depends on the structure | Merchants and payment companies |
A few terms in that table, in plain words. Recourse means you must repay the funder if your customer doesn't pay.
Non-recourse means the funder takes that loss. Eligible receivables are the invoices a funder agrees to lend against, usually ones that aren't too old.
Card settlement financing covers card sales that have already happened and are waiting a few days to settle, so it is short and tied to real, completed payments. A merchant cash advance is a separate product that buys a share of future card sales.
Card settlement financing is the type CREDI vaults fund, alongside trade payments that settle in days to weeks.
How this connects to CREDI
CREDI is infrastructure for private credit: an onchain layer that connects capital from liquidity providers (LPs) to real-world receivables. Every type in the table above needs someone to put up the cash, and CREDI works on that funding side.
LPs deposit stablecoins such as USDC, digital dollars designed to hold a value of $1, into a CREDI vault. Vault capital finances card and trade payments waiting to settle, and the vault is repaid when each payment settles.
LPs get a fixed rate set on the day of deposit.
Keep reading: the next sections explain advance rates, a worked cost example, what funders look at, the risks on both sides, and who funds receivables today. If you're new to the asset class, start with what private credit is.
How Advance Rates and Borrowing Bases Work
The advance rate is the share of a receivable's value the funder pays you upfront. The rest is held back as a reserve, a safety buffer, and released minus fees when your customer pays.
The reserve protects the funder against invoices that are paid late, disputed or never paid.
Funders advance only against receivables they class as eligible. The U.S. bank regulator's handbook on asset-based lending (OCC) says common advance rates "range from 70 percent to 85 percent of eligible accounts receivable." It also lists the rules that shrink what counts:
- Age: an invoice usually stops counting once it's far overdue, for example 90 days past due on 30-day terms.
- Bad payers: if enough of one customer's invoices go overdue, all of that customer's invoices can be dropped.
- Concentration: too much owed by a single customer lowers what you can borrow.
- Dilution: returns, discounts and disputes shrink the value of the receivables.
Your eligible receivables multiplied by the advance rate gives the borrowing base, the most you can draw. In asset-based lending, the credit line moves up and down with it.
Short receivables pass these tests easily. A card payment that settles in a few days rarely gets old enough to drop out.
That's part of why CREDI focuses on short-duration receivables: the cash comes back quickly, and problems show up fast.
A Worked Example: What Receivables Financing Really Costs
The cost depends on the fee and on how long your customer takes to pay. Most funders charge a fee for each period, so the same deal costs more when the customer is slow.
The numbers below are illustrative only. They are not quotes from any provider and not CREDI's terms.
A supplier invoices a retailer $100,000 on net 60 terms. A funder offers an 80% advance and a fee of 2% of the invoice value for each 30 days.
| Step (illustrative) | Customer pays in 60 days | Customer pays in 90 days |
|---|---|---|
| Cash advanced on day 1 (80%) | $80,000 | $80,000 |
| Reserve held back (20%) | $20,000 | $20,000 |
| Fee (2% per 30 days) | $4,000 | $6,000 |
| Reserve released after payment | $16,000 | $14,000 |
| Total cash received | $96,000 | $94,000 |
| Fee as % of cash advanced | 5.0% | 7.5% |
| Simple yearly cost (not an APR) | about 30% | about 30% |
Two lessons follow. A "2% fee" is about 30% as a simple yearly cost on the cash actually advanced.
And every extra month the customer takes adds another fee, which is why days sales outstanding (DSO), the average number of days it takes to collect a sale, matters so much.
Now compare a card receivable. A merchant has $10,000 of card sales waiting a few days to settle.
The money is out for days, so the fee in dollars is small. The risks are specific to cards: chargebacks (card payments reversed after a dispute), refunds, and a company in the payment chain failing.
That short timeline is what CREDI vaults are built on. Capital is out for days to weeks, comes back at settlement and is put to work again, while LPs earn a rate fixed on the day they deposit.
What Funders Look At
Funders mostly look at who owes you money, along with your own business. Strong, varied customers can get a young business funded.
One customer making up most of your sales can make an established business hard to fund.
What a funder will usually ask for:
- An AR aging report: a list of what each customer owes, grouped by how overdue it is.
- Customer concentration: how much your top five customers owe.
- Dilution history: credit notes, returns and disputes as a share of sales.
- Proof the receivables are real: contracts, delivery records or card processor statements.
- Existing claims: whether another lender already has rights over your receivables.
- For card receivables: chargeback and refund rates, and how settlement money flows.
Invoicing quickly, chasing late payers and settling disputes improve every item on that list and lower what you pay.
CREDI applies the same thinking from the investor's side. Card receivables come with a clear payer, the card network, and a short, predictable settlement date, and CREDI's book is attested by an independent party, meaning an outside firm checks and confirms the data.
Risks to Watch on Both Sides
Receivables financing is backed by real sales, and it still carries risk for the business and for the funder. A receivable is only as good as the customer behind it, the documents that prove it and the process that collects it.
For the business:
- Recourse: in most invoice financing and recourse factoring, you repay the funder if your customer doesn't pay.
- Cost creep: fees per period add up when collections slow down, as the worked example shows.
- Customer relationships: in factoring, your customers pay a third party, which some businesses prefer to avoid.
For the funder or investor:
- Credit risk: the chance the end customer, or a company in the card and payment chain, doesn't pay.
- Dilution and fraud: invoices that are disputed, inflated or fake.
- Concentration: too much exposure to a few customers, sectors or partners.
- Operational risk: money has to flow back through the right accounts on time.
These are the risks a CREDI LP takes on too. Payments can arrive late or fail to settle, a partner in the payment chain could fail, and the vault's smart contracts and the stablecoin itself carry technical risk.
In exchange, the receivables are short, the rate is fixed at deposit, and vault activity is recorded onchain.
Who Funds Receivables Today?
Receivables are funded by banks, specialist finance companies, private credit funds and, more recently, onchain vaults. Each one funds the same kind of asset with its own capital.
- Banks are the traditional source, through asset-based lending lines and supply chain finance programs. Capital rules and their own balance sheets limit how much they can do.
- Specialist lenders and fintechs serve much of the small business end. The Fed survey found the share of applicants going to online lenders rose from 17% in 2020 to 29%. In the UK, independent providers held 30% of invoice finance clients in 2025, up from 27% a year earlier, according to the British Business Bank.
- Private credit funds, which lend outside the banking system, increasingly buy or fund pools of receivables. The BIS estimated that private credit loan volumes grew from around $100 billion in 2010 to over $1.2 trillion.
- Onchain vaults are the newest layer. Investors deposit stablecoins, the capital funds real receivables under set rules, and activity is recorded on a public blockchain. Our guide to what onchain private credit is explains how it works.
CREDI is one of those onchain vaults. LPs deposit USDC, choose a lock period of 3 to 24 months at deposit (published terms, November 2026) and get a fixed rate set that day.
Vault capital finances card and trade payments that settle in days to weeks. As of October 2026, CREDI has funded $16.37M to date with 0 realized losses to date.
Past results don't guarantee future ones. Our piece on the illusion of yield explains why the source of a yield matters.
Frequently Asked Questions
Is accounts receivable financing a loan?
It depends on the type. Invoice financing and asset-based lending are loans backed by your receivables.
Factoring is usually a sale of the receivables. The difference changes who collects, who carries a default and how it shows on your balance sheet.
Can a startup get receivables financing?
Often, yes. Funders weigh your customers' ability to pay heavily, so a young company that invoices large, reliable customers can qualify before it would get an unsecured bank loan.
Having most sales with one customer is the usual obstacle.
What happens if my customer never pays?
With recourse, you repay the advance, usually by swapping in another invoice or paying cash. With non-recourse factoring, the factor absorbs a loss caused by the customer going bust and usually charges more for it.
Disputes about the goods or service usually stay with you either way.
How fast can I get the money?
The first setup takes the longest, because the funder reviews your customers, documents and any existing claims. Once a facility is running, new invoices are usually funded much faster.
How does CREDI fit into accounts receivable financing?
CREDI works on the funding side. LPs deposit stablecoins into a CREDI vault, and vault capital finances card and trade payments waiting to settle.
The vault is repaid when each payment settles, and LPs earn a fixed rate set on the day of deposit.
Fund the Wait, Earn a Fixed Rate
Receivables financing works because the sale has already happened. The open questions are who funds the wait and who carries the risk.
CREDI connects LP capital to that wait through vaults that finance short-duration card and trade payments, with a fixed rate set at deposit and activity recorded onchain. To see how it works, explore CREDI →
This article is for information only and is not financial, investment or legal advice.


